The Best Tenant Screening Services: Our 2026 Guide
Google “best tenant screening service” in 2026 and you’ll be met with a wall of sponsored results, self-promotional listicles touting one service over another, and confusing offers for “free tenant screening.” Soon you may have a dozen or more browser tabs open comparing SmartMove, RentSpree, Avail, Apartments.com, Zillow Rental Manager, and whoever else happens to get a random mention in a Reddit thread.
Most tenant screening services claim their reports are comprehensive and reliable. Some even claim to be “the best” service. But what actually differentiates a tenant screening service? Do I get more when I pay more? Which metrics or reports are best at predicting on time rent payments and tenant reliability? Should I pay or ask the tenant to pay? What’s the best way to verify income? Should I require landlord references?
In this updated 2026 tenant screening guide, we tackle all of these questions and more.
What Really Matters in Tenant Screening?
Most tenant screening services designed for independent landlords have spent huge sums of time and money trying to convince their customers that their particular way of screening tenants is somehow superior. They do this by creating proprietary “scoring” schemes that sit on top of standard credit pulls or by touting the number of data sources they have access to across the country. Prices are all over the map and the typical buffet of optional add-on services only serves to further complicate purchasing decisions. Layer on a restrictive patchwork of tenant screening regulations and you have a perfect storm in which many rental property owners are increasingly confused about how much they can rely on any particular report.
According to a 2022 CFPB market study, which seems to be the most detailed recent look at the tenant screening industry, there is not an overwhelming consensus of published, independent evidence that basic tenant screening reports reliably predict future tenant behavior. This is in part due to rampant inaccuracies that lurk within the underlying data sources, but also says a lot about the human capacity for personal and professional growth. It also begs the question, so what is a good forward indicator? How can I give myself the best shot at being paid on time every time?
As it turns out, the most important factors to consider when evaluating prospective tenants, may in fact be (verified) income and prior landlord references. Surprisingly, not every tenant screening service offers these and some of those that do, don’t do it very well. These two critical aspects are often sold as add-ons to the basic credit and background check reports, despite our view that they are essential elements of a proper tenant evaluation.
2026 Pricing & Feature Comparison for Independent Landlords
Now that we’ve established where tenant screening can sometimes fall short and how to best protect yourself from fraud, let’s move on and compare actual services. The prices and other details quoted below were checked against publicly available information as of September 2026.
| Provider | Full Package Price* | Who Pays* | Income Verification Method* |
|---|---|---|---|
| Apartments.com | $32 | Applicant | Document upload |
| Avail | $55 | Either | Document upload |
| Baselane | $49.99 | Applicant | Bank-link verified |
| Clara | $49 | Applicant | Bank-link verified |
| DoorLoop | $45 | Either | Hybrid |
| Hemlane | $40 | Applicant | Hybrid |
| Innago | $40–45 | Applicant | Hybrid |
| Keycheck / Furnished Finder | $44.99 | Either | Document upload |
| Landlord Studio | $45-55 | Either | Document upload |
| MyRental | $43.99 | Either | Algorithmic / Document upload |
| Rental Beast | $49 | Applicant | Document upload |
| RentPrep / Stessa | $64 | Either | Bank-link verified |
| RentRedi | $49.99 | Applicant | Bank-link verified |
| RentSpree | $49.99 | Either | Bank-link verified |
| SingleKey | $39.99 | Either | Bank-link verified |
| TenantCloud | $50 | Applicant | Algorithmic / Document upload |
| TransUnion (SmartMove) | $49 | Either | Algorithmic / Document upload |
| TurboTenant | $45–55 | Either | Algorithmic / Document upload |
| Zillow Rental Manager | $35 | Applicant | Document upload |
There are a few important details worth keeping mind as you digest this table:
- The tenant screening industry is a bit weird in that many services partner with other (competing) services for various pieces of the screening workflow. For example, TransUnion provides most of the credit, criminal, and eviction records for many of the services shown above, despite the fact that SmartMove competes directly for the same landlord customers.
- Prices range from $32 all the way up to $64, but of course not all “full” screening packages are equivalent. Many services on this list offer a “basic” report at a low teaser price and then hit you up for add-ons that can significantly increase the total cost. Most of the players on this list require a full account set up before you can screen anyone, and some of those offer paid accounts that come with discounted screening. A few offer tenant screening on a standalone basis without having to choose a subscription tier.
- You really do need to read the fine print to understand what you’re getting. Is an “application” included? Are court records actually accessible for my state? Are landlord references included? Is income validated through bank API or is it done on the honor system based on document uploads? Will this service also push for my rent collection business on the back end of the tenant screening?
Because partnerships and pricing are always in flux, we recommend keeping these questions handy. Use them to quiz the AI-powered chatbots that most of these services now offer on their websites. That’s often the best way to make sure you have the most up-to-date specs and can feel confident that you’re getting a truly “comprehensive” report.
For most self-managing landlords looking for standalone tenant screening without full account set up, we currently recommend RentSpree and RentPrep as your most thorough screening options. If you don’t care about bank-linked income validation, then TransUnion Smart Move and MyRental are also worthy options. The challenge with all of the others on this list is that tenant screening is just one aspect of their larger subscription packages. One of these might indeed be the best fit for you, but that requires a larger conversation that includes evaluating the best landlord accounting software, among other aspects.
The Tenant Screening Industry’s Open Secret
Every screening tool wants you to believe it has some proprietary edge like a smarter algorithm, a deeper database, or a more “comprehensive” report. But once you peel back the marketing and look under the hood, a lot of these screening services are essentially providing the same data (from the same data sources), albeit with different wrappers.
TransUnion supplies the underlying credit and criminal data infrastructure behind nearly every major screening product landlords use today, including SmartMove, RentSpree, Avail, Zillow Rental Manager, Apartments.com, TenantCloud, and RentPrep/Stessa, among others. When you pay $35 through one platform and $49 through another, you’re largely paying for packaging, turnaround speed, and perhaps some minor conveniences. You generally should not expect to see fundamentally different information about the applicant across most of these services.
That’s not a knock on TransUnion. Their data is directionally useful and widely relied upon due to the company’s strong track record serving the tenant screening industry. Equifax and Experian have built similar databases, but historically have not made the same investments in pursuing the landlord/investor customer segment. That said, the CFPB’s review found the broader tenant screening industry itself to be surprisingly opaque, with no federal registration requirement for screening companies. There are probably hundreds of companies offering tenant screening services but there are only about 10-15 services that independent landlords will find worthwhile to consider.
Why Many Credit & Background Checks Fall Short
1. Credit Scores Mostly Ignore Rent
A credit score is a proxy for how someone handles revolving credit and installment loans, including credit cards, auto loans, student debt, mortgages, and more. It was not specifically constructed to opine on someone’s likelihood of paying rent on time. Prior rent payment performance is notably absent from the vast majority of credit reports, although that is now starting to change, albeit very slowly.
The CFPB estimates that only 1.7% to 2.3% of adults living in rental housing have a rent-payment tradeline in their credit file. That means the credit score you see, for the vast majority of applicants, reveals no direct information about most people’s single largest recurring monthly obligation. You’re inferring rent reliability from card and loan behavior, which is a reasonable proxy, but still only a proxy nonetheless.
When it comes down to it, most renters (especially in states with landlord-favorable eviction laws) will prioritize making their monthly rent payment before all other obligations. So, while the fact that someone might be chronically behind on a credit card payment does say something about their overall financial situation, there might also be a track record of perfect rental performance hiding behind the low credit score.
2. Eviction Records are Noisier than They Seem
While eviction history feels like a clean signal that landlords can rely on to screen out the highest risk candidates, it’s a bit messier in practice than you might expect.
An estimated 3.6 million eviction records are filed each year, and a peer-reviewed study of court records across 12 states, cited in the CFPB report, found that 22% of state eviction cases are ambiguous or contain outright false information. Many of these discrepancies can be attributed to inconsistent record keeping and “unresolved” filings, in which the landlord dropped the case for one reason or another. State laws vary widely and some types of eviction records are purged in some states but retained in others, which can lead to false negatives in which a tenant with a history of being evicted comes back with a clean record.
Alternatively, CFPB research and a 2016 Federal Reserve Bank of Atlanta study both found that large corporate landlords file eviction notices at substantially higher rates than smaller ones, even after controlling for property quality and location. This suggests that some institutional landlords likely use eviction filings as a routine rent-collection tactic rather than a last resort. When that happens, the initial filing can still show up on the applicant’s record even if they were merely late on rent and subsequently got current.
In either scenario, screening tools generally lack essential context when it comes to eviction records, which might lead you to pass on a quality tenant or approve someone who has in fact been evicted in the past. Either way, we think it’s best to use eviction reporting as one data point among many. It’s also wise to never assume that a “clean” eviction report is a 100% guarantee that someone has never been the subject of an eviction proceeding.
3. Criminal History: Shelf Life & Legal Limits
Background checks often seem to present criminal history as a permanent black mark that forever disqualifies someone from rental housing eligibility. Statistically, only some types of crime are meaningful predictors of future rental performance, and even then, the predictive power fades over time. From a legal perspective, it’s also becoming much more difficult to deny housing based on criminal history alone.
One study of 15 offense categories from a coalition of housing providers found 11 of them showed no meaningful link to negative housing outcomes at all. For the categories that did matter, the effect faded over time. The impact of certain misdemeanors became statistically insignificant after two years and some felonies after about 5 years. In 2022, HUD issued formal guidance warning that automatically rejecting any applicant with a criminal or arrest record, without an individualized assessment that considers the broader context, can violate the Fair Housing Act. And a growing list of cities and states, including Seattle, San Francisco, Portland, Cook County (Chicago), and New Jersey, now restrict the use of criminal history in tenant screening decisions.
That doesn’t mean criminal history is irrelevant. Recency and severity of the crime still matter a great deal, and you can and should use criminal background checks as a key screening factor alongside other important checks. But giving a decade-old conviction for a minor offense the same weight as a more recent serious crime isn’t always solid risk management and it may even run you afoul of local, state, or federal housing regulations.
4. Identity (Mis)Matching is a Big Problem
A lot of tenant screening services use automated systems match court records to applicants using names rather than other unique identifiers, and sometimes they only use a partial name or initial (“wildcard matching”). This is far less reliable than a full identity match on name, date of birth, and address. This shortcut works fine much of the time but it also leads to false positives in which someone else’s criminal records can be mistakenly associated with your applicant.
Taken as a whole, these data quality issues and matching problems appear to undermine claims from tenant screening platforms that their reports are “comprehensive” and predictive of future tenant behavior. So, are there other more reliable indicators?
Key Differentiators: How Platforms Verify Income and Liquidity
If credit and criminal data can’t always reliably tell you whether someone can pay rent, proof of income and cash in the bank become key factors to assess and verify. The problem is that verification can be faked and applicants are now using AI tools to create very authentic looking paystubs and other key documents. Not every platform verifies income and liquidity in the same way, and this is a critical differentiator among tenant screening services.
When we look across services, we see a three-tier hierarchy of verification quality.
Tier 1: The Honor System
This is the most common, and weakest, verification method. The applicant uploads a PDF paystub and bank statement (or screenshot), and the platform accepts it at face value. You can of course view the documents, but do you really know what you’re looking for? Every company’s paystubs look different.
The problem is that forged paystubs are relatively cheap and easy to produce, and some estimates are that more than 10% of rental applications now contain a fraudulent document of some kind. This might include fake evidence of income, an altered bank statement, or an ID that doesn’t hold up. Manual review by the platforms catches some of these shenanigans, but not reliably in every instance. Zillow Rental Manager, Apartments.com, MyRental, and Avail are common examples of platforms built primarily on this document-upload model. This approach to verification is better than nothing, but it’s also quite vulnerable to a determined bad actor.
Tier 2: Algorithmic Estimation
Instead of relying on the honor system via document uploads, some platforms estimate income based on credit behavior, including spending patterns, credit utilization, and account types. TransUnion’s Income Insights (bundled into SmartMove’s Premium tier) works this way, and similar estimation logic may also be in use by Hemlane and TenantCloud’s add-on income verification report.
This is harder to fake than a PDF, since it’s derived from the same bureau data feeding the credit check. But it’s still an estimate, not a true verification, and TransUnion’s own materials caveat that if an applicant is simply a heavy saver rather than a heavy spender, the algorithm might undervalue their actual income level.
Tier 3: Direct Bank-Linked Verification
The strongest verification method in use by today’s tenant screening companies looks directly into the applicant’s bank account via an API like Plaid or Finicity, to pull their actual transaction history. This typically includes deposits, balances, and cash flow information, which is then used to verify the self-reported income figures on the application. It’s all done with the applicant’s express consent and is typically quick and efficient.
Forgery and deception are essentially non-issues with this method because the numbers come straight from the actual bank. RentSpree (via Finicity) and RentRedi (via Plaid) have built this verification method into their standard workflow. TurboTenant partnered with Rent Butter in 2025, which layers bank-account linking, payroll-provider connections, and document upload into a single fraud-detection service. On the enterprise side, TransUnion has also deepened its own bank and payroll-verification partnership with Truework, so this capability is also increasingly available at scale for larger PMs, institutional owners, and lenders.
Our best guess is that bank-linked verification will eventually become the default method for nearly all tenant screening services, but it may take a while to get there and some legacy products may persist for a while. That’s why we feel it’s worth paying attention to exactly how your screening platform verifies income. The bank-link process is a real innovation, protects you from fraud, and often justifies the higher price tag in many leasing situations. If you don’t go this route, just be aware of the risks that come with other types of “verification.”
How to Think About Landlord-Pay vs. Tenant-Pay
The pricing table above also indicates whether each service requires the applicant to pay or allows the landlord to choose who pays. We very much prefer services that allow the landlord to make this decision as it shows a deeper commitment and level of investment in the overall offering. The flexibility to pay for screenings instead of asking the tenant to pay is also something that some landlords appreciate and will use in some situations, particularly when state laws cap the amount that the tenant can be asked to pay.
The Case for Tenant-Pay
Passing the $32–64 fee onto the applicant is the most common configuration and it’s popular for a couple of key reasons. First, it allows the tenant screening service to advertise that it’s “free for landlords.” Well, of course it’s not actually free. Someone is going to pay and that someone is your applicant. For the landlord, tenant-pay allows you to run as many screenings as necessary without incurring any direct costs. If you have six applicants apply for one unit, you can ask each one to pay for their own screening instead of incurring six charges on your side of the ledger.
We think the most convincing argument for tenant-pay is actually that it’s an effective way to filter out some unserious candidates. If someone isn’t willing to pay $49 for a screening report, how serious can they really be? If they seem very concerned about the cost, then what might that say about their ability to pay rent in the future? Just keep in mind that this line of thought only extends so far before it starts to bend. A clearly qualified applicant in a tight rental market might be juggling five or more applications at the same time and could merely be trying to avoid spending hundreds of dollars to land an apartment.
On the flip side, in a down market where rentals are easy to come by, requiring an upfront screening fee before you’ll consider someone can quietly shrink your applicant pool. You won’t really know who’s not bothering to apply. You’ll just hear crickets.
The Case for Landlord-Pay
Covering the screening fee yourself removes the friction entirely, which can widen your funnel and speed up leasing. This approach is particularly useful in a slower market, for a higher-priced unit, or anywhere you’re competing against other listings that similarly absorb the cost of tenant screening. It can also work as a differentiator in your listing copy (“no application fee”) if you’re looking to stand out and increase the number and/or pace of applications.
The higher potential cost of using this approach is obvious. You’re now paying to screen every applicant, not just the one that ends up moving into the unit. If your typical funnel is five or six applicants per accepted tenant, you’ll be on the hook for five or six screening fees instead of none.
The Middle Ground
A few platforms don’t force a binary choice. SmartMove, RentPrep, and SingleKey, for example, all let you pick who pays without having to set a permanent default. This means you can default to applicant-pay for routine listings and then switch to landlord-pay selectively. You might do this when a unit has been sitting vacant for more than 30 days or per some other well-defined criteria that you apply consistently across all applicants for a particular housing opportunity.
Note Recent Legal & Regulatory Changes
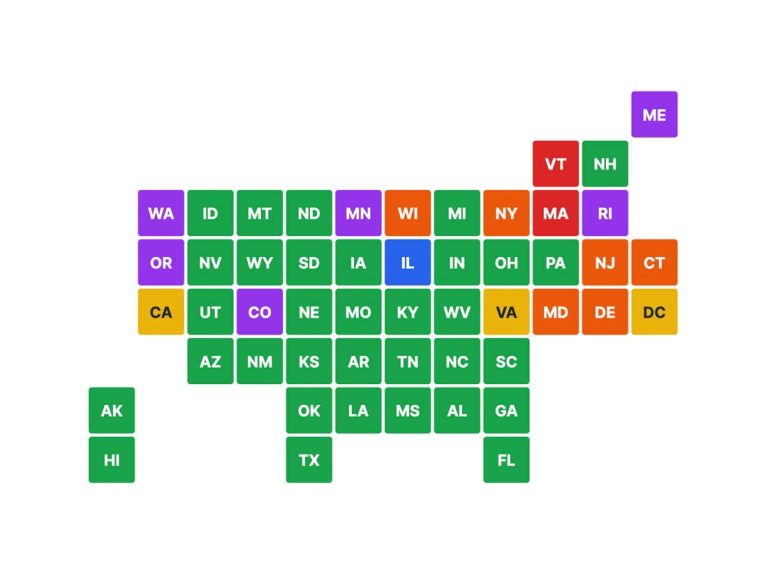
The regulatory environment is shifting rapidly. Tenant screening fee caps are popping up in cities and states across the country, which may prevent you from passing on the entire screening cost, depending on which service you select.
California caps the tenant-facing application screening fee at $30 per applicant (adjusted annually for inflation) and New York caps it at $20. These caps generally govern what you can charge an applicant, not what the screening service charges you. That means you’re absorbing the difference in states where a cap applies. Most services handle these situations for you relatively smoothly, even when you choose tenant-pay.
Another growing trend is the requirement that landlords accept reusable screening reports. In states with portable-report laws (California, Maryland, Washington) or on platforms that allow report-sharing (Zillow Rental Manager and Apartments.com), this can prevent you from requiring a tenant to pay for a fresh screening report if they’ve already purchased one recently. Zillow and Apartments.com both let applicants reuse a report across up to 10 landlords for 30 days, while RentSpree’s reports stay valid for 30 days across all properties.
Landlord Reference Checks Are Important
We said up top that verified income and prior landlord references may be the two factors that actually matter most when it comes to predicting future renter behavior. Surprisingly, a lot of landlords either skip this step entirely or do it so casually it’s barely worth the phone call.
How to Collect Landlord References
Almost every rental application asks for references, typically current and prior landlord name, phone number, and dates of tenancy. Some platforms like Avail will even auto-dial or email previous landlords with a short standardized questionnaire on your behalf, so you never have to make the call yourself.
As convenient as that may sound, it’s probably not the most thorough or effective way to check references. Tech companies love to automate everything and take humans out of the loop, but in this instance there’s really no substitute for a live conversation. We don’t recommend cutting corners when checking landlord references.
Try to Talk to Two Different Landlords
If you only connect with your applicant’s current landlord, you may in for a rude surprise down the road. A landlord who’s desperate to get rid of a problem tenant has every reason to give that tenant a glowing reference to smooth their exit. Unfortunately, this is a well-known incentives problem that smart owners know can undermine their screening efforts. That’s why it’s best never to rely on just one positive reference.
We think it’s best to always ask for two landlord reference, including the current and most recent previous landlord. The prior landlord has no obvious reason to lie and can generally be expected to supply an accurate signal.
The Questions That Matter Most
A solid reference check involves more than simply asking, “were they a good tenant?” Instead, ask specific factual questions that are harder to finesse:
- Did they pay rent on time every month? If not, how often were they late?
- Did you ever have to send a formal notice, file for eviction, or involve a collections agency?
- Did they give proper notice before moving out or did they break the lease?
- Was there any damage to the unit beyond normal wear and tear?
- Were there noise complaints, disputes with neighbors, or unauthorized occupants/pets?
- Would you rent to this person again?
That last question on the list is particularly important. A landlord who hesitates, gives a non-answer, or won’t commit to a clear yes is telling you something even if they never say it out loud. This is why it’s extra important to connect live on the phone rather than simply communicating via text or email.
Finally, keep in mind that it’s usually best to ask every applicant’s references the same set of questions and to keep a record of the answers. This helps keep your process consistent and fair across all applicants.
Watch for Fake Landlords
Just like the AI-generated paystub problem we covered earlier, references aren’t immune to fraud. It’s not unheard of for an applicant to list a friend or family member as a “previous landlord” to vouch for them. Fortunately, there are a few quick ways to sanity-check that the person on the other end of the phone is real:
- Ask them to confirm the property address and the applicant’s move-in/move-out dates before you volunteer that information.
- Cross-reference the property address against county assessor records to confirm the person you’re calling actually owns or manages that address.
- If something feels off, ask a follow-up question only the real landlord would know, like the unit number or the exact rent amount.
Our Take
If a platform you’re using has automated reference-checking built in, use it as a first pass only, not as a substitute for connecting with landlord references over the phone. If your platform doesn’t offer it, don’t skip this step just because it takes extra time and effort. You might be surprised how often a five-minute phone call identifies problems that no credit score, criminal check, or income verification tool ever will.
Frequently Asked Questions
Not necessarily. Most platforms use an applicant-paid model where the prospective tenant covers the $32–$64 report cost directly, and you never see an invoice. Nationally, roughly two-thirds of renters report paying some kind of application fee, most of it earmarked for screening. A few services (SmartMove, RentPrep, SingleKey) let either party pay. Landlord-pay can sometimes help owners speed up leasing activity in a loose market with lots of available units.
A standard FICO or VantageScore is built to predict general credit risk, which is how someone handles credit cards and loans. TransUnion’s ResidentScore is trained specifically on rental payment and eviction outcomes, weighing factors differently to predict landlord-relevant risk. TransUnion markets ResidentScore as identifying eviction risk roughly 15% more accurately than a traditional credit score, but that’s based on a 2016 internal TransUnion study that does not appear to have been audited or updated recently.
Treat them as a starting point, not proof. Document-based verification is the tier most exposed to forgery as editable PDFs and convincing fakes are widely available. One industry estimate puts fraudulent-document rates at roughly 1 in 6 applications. If a platform you’re using offers bank-linked verification we recommend using that instead, even if it’s a paid upgrade.
Sometimes they are less accurate than you might expect. A 12-state study of 3.6 million eviction court records found 22% were ambiguous or outright false, driven mostly by inconsistent state records about how cases were resolved. A filing that was later dismissed, settled, or even decided in the tenant’s favor can still show up as a red flag with no context attached, because most screening reports capture the initial filing rather than the final outcome.
Not exactly. HUD’s 2022 guidance treats a blanket policy of rejecting every applicant with any criminal or arrest history as a potential Fair Housing Act violation, because it can produce a discriminatory effect without an individualized basis. A growing number of cities and states like Seattle, San Francisco, Portland, Cook County/Chicago, and New Jersey go even further and restrict the use of criminal history in tenant screening in very specific and targeted ways. It’s best to make sure you have a clearly written policy around criminal convictions (recency, severity, relevance) rather than a blanket disqualification rule. Check your local and state rules before finalizing your policy.
A credit report only covers what a lender or creditor reported, which typically includes card and loan payment history, balances, and public records like bankruptcies. It generally doesn’t include eviction filings (these were removed from standard credit reports industry-wide between 2017 and 2018) or criminal records. A tenant screening report packages that credit data together with eviction history, criminal background (where legally permitted), and sometimes income verification and rental history. This is why the vast majority of landlords order screening reports rather than standalone credit pulls.
On some platforms, yes. Zillow Rental Manager and Apartments.com let applicants share a single report with up to 10 landlords within a 30-day window. RentSpree’s reports stay valid for 30 days across properties. Separately, California, Maryland, and Washington have passed laws permitting “reusable” or portable screening reports more broadly, specifically to cut down on renters paying repeated application fees. Landlords in those states aren’t always required to accept a reusable report, but many now do.
Federal law (the FCRA) gives applicants the right to dispute inaccurate information with the screening company, and landlords are required to send an adverse action notice (including the name of the screening company used) if a rental decision is based even partly on the report. In practice, dispute processes vary widely by provider. Some accept disputes online, others only by mail, and CFPB complaint data shows response times and resolution rates are inconsistent across the industry. If something looks off or it’s obvious there’s an identity or name mismatch, it may be worth pausing your decision to give the applicant a chance to explain or dispute the reported information.
Across the providers independent landlords use most frequently, you can expect costs from $32 to $64 per applicant for a tenant screening package. Credit, criminal, and eviction history are nearly always included, while income/employment verification is more often found at the higher end of the price range.