Why Maui’s Bill 9 Will Fail in Wailea and Kapalua Resort Areas
When Maui County moved to phase out transient vacation rental (TVR) rights on grandfathered “Minatoya List” properties via Bill 9 in late-2025, the policy was packaged as a direct solution to the island’s acute housing shortage. The legislative theory was simple (too simple, actually): extinguish short-term rental rights in apartment-zoned districts, and thousands of luxury condo owners will magically decide they have no better option than to serve up affordable long-term housing for local families.
In master-planned resort corridors like Wailea and Kapalua, that premise is not only a betrayal of the County’s own legal opinion from 2001, but it collapses under basic balance-sheet arithmetic.
These resort complexes are not traditional multi-family apartment buildings with centralized, low-overhead operational models and a single owner. They are individually owned, fee-simple condominium regimes burdened with high, non-negotiable carrying costs. These projects were entitled and built as condos in the 1970s and 1980s with individual units widely marketed to off-island investors.
Stripping these properties of transient vacation rental rights does not somehow turn them into “apartment” complexes, nor will it drive down values so severely that local residents can swoop in and purchase a luxury condo at an “affordable” price.
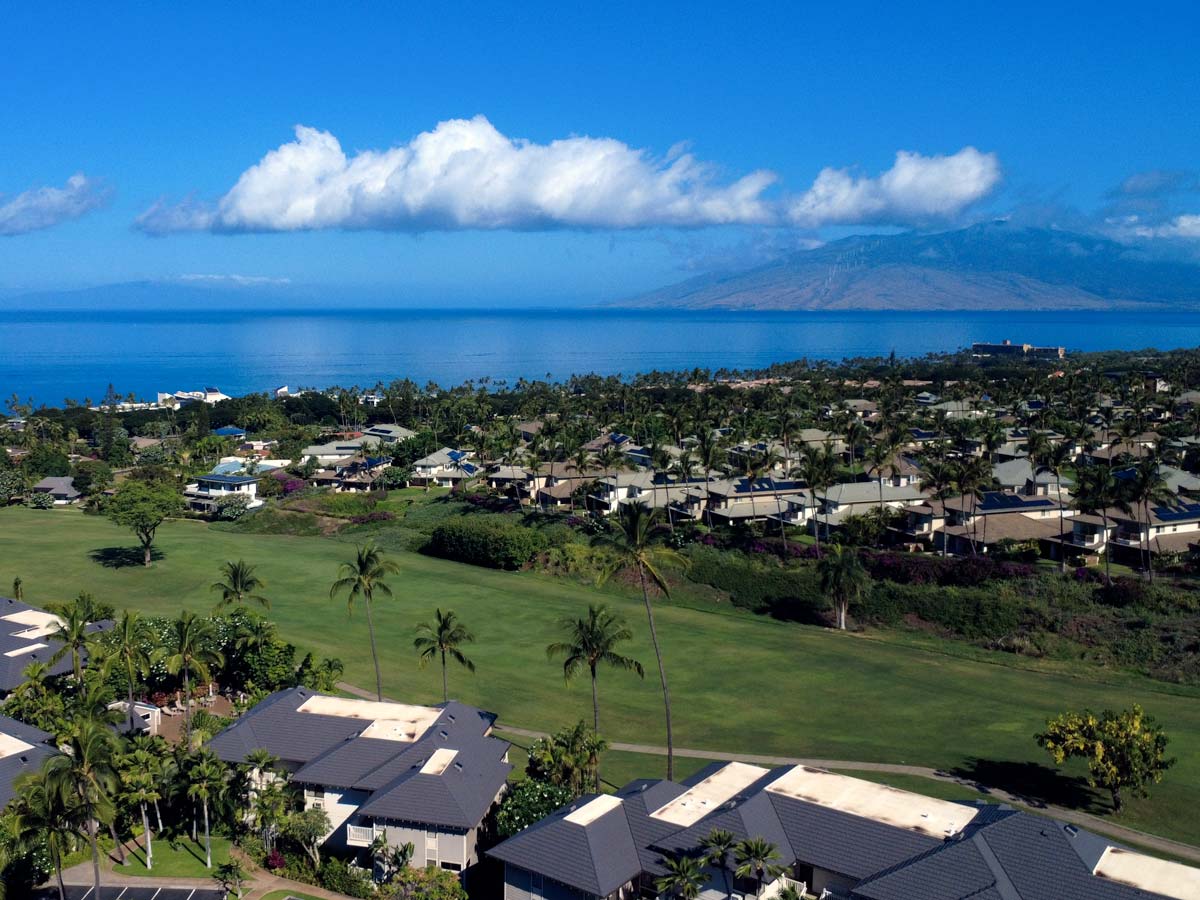
To illustrate why, we examine the baseline economics of a representative $1M resort condominium in Wailea (valued at $1.5M before Bill 9) that currently generates $100,000 in gross annual short-term rental receipts. The policy failure of Bill 9 in luxury resort areas is driven by two market realities: 1) the mathematical impossibility of the benevolent landlord, and 2) the luxury second-home price floor.
Argument 1: The “Benevolent Landlord” Fallacy
The first core assumption of the legislation is that current owners, stripped of STR revenues, will pivot their $1M units into the long-term rental (LTR) market to house local residents.
A basic cash flow analysis demonstrates why this will not happen. Fixed operating overhead in resort communities exists independently of debt service or occupancy. Before factoring in a single dollar of mortgage principal, property management, or property taxes, non-negotiable overhead (AOAO dues, master association fees, and hazard insurance) costs roughly $1,700 every single month.
Here is the operational reality of converting a 2-bedroom STR unit now valued at $1M into a long-term rental, assuming a market-rate residential lease at $4,000 per month:
| Line Item | Lawful STR ($1M Basis) | Forced LTR ($1M Basis) |
|---|---|---|
| Gross Potential Revenue | $100,000 / yr | $48,000 / yr ($4,000/mo) |
| • Maui Real Property Taxes | -$13,200 / yr ($1,100/mo) | -$2,320 / yr ($193/mo) |
| • Hawaii State TAT (11.00%) | -$11,000 / yr ($917/mo) | $0 |
| • Maui County TAT / MCTAT (3.0%) | -$3,000 / yr ($250/mo) | $0 |
| • Hawaii General Excise Tax / GET (4.5%) | -$4,500 / yr ($375/mo) | -$2,160 / yr ($180/mo) |
| • Fixed HOA / Master / Insurance / R&M | -$20,300 / yr ($1,692/mo) | -$20,300 / yr ($1,692/mo) |
| • Property Management | -$20,000 / yr (20% STR) | -$4,800 / yr (10% LTR) |
| • Cleanings / Utilities / Supplies | -$16,800 / yr | $0 (Tenant pays utilities) |
| Total Expenses & Taxes | -$88,800 / yr | -$29,580 / yr |
| Net Operating Income (NOI) | +$11,200 / yr | +$18,420 / yr |
| Debt Service (75% LTV @ 7.00%) | -$59,877 / yr ($4,990/mo) | -$59,877 / yr ($4,990/mo) |
| Net Cash Flow (Leveraged) | -$48,677 / yr | -$41,457 / yr |
| Unleveraged Cap Rate (All-Cash) | 1.12% | 1.84% |
It may be tempting to look at the above analysis and say, “well the investor is actually better off financially doing long-term rental instead of short-term, so what’s the big deal?” And while that may be mathematically true (both investment scenarios are really awful), it’s only part of the story.
The rest of the story is that an STR owner accepts tight or negative operational cash flow because the asset provides a critical non-financial return: personal lifestyle utility. The owner retains access to the home in a premier resort market for several weeks (or months) each year, while transient rental revenue subsidizes some of the property’s underlying debt, AOAO fees, and master association assessments.
And that’s not all that’s subsidized by the owner’s short-term rental operations. Local and state government operations are also supported to the tune of more than $30,000 in tax revenue per unit, while the LTR scenario generates less than $5,000 of annual tax revenue. That’s an 83% reduction in tax revenue resulting in a $25,000 tax collection shortfall from just one condominium unit.
Converting to an LTR destroys that personal lifestyle utility entirely. The owner surrenders 100% of possessory rights to a long-term tenant for 365 days a year. Even for an all-cash LTR owner with zero mortgage debt, a $1M asset generating $18,420 in NOI produces a 1.84% cap rate (which is well below risk-free Treasury bills), while exposing the owner to tenant wear-and-tear and capital assessment risks.
Rational property owners do not accept a sub-2% yield in exchange for surrendering their right to personally use their property throughout the year. Who exactly does Maui County think is going to own and operate these units as long-term rentals when the math is so clearly broken?
Argument 2: The Second-Home Price Floor
Because existing owners cannot justify holding these units as long-term rentals, cash-flow pressure will force many to sell. Bill 9’s second major assumption is that this forced selling will cause purchase prices to plummet to levels affordable for Maui’s local workforce.
This ignores the structural presence of mainland capital in high-amenity resort markets, irrespective of whether short-term rental activity is permitted in a given complex. When a luxury condo’s STR rights are extinguished, the value does not plummet until it reaches a price point accessible to a local family. It simply drifts into “bargain” territory for affluent mainland second-home buyers.
For high-net-worth buyers, an $800K to $1M lock-and-leave condo alongside championship golf courses is an attractive private getaway. They buy in cash, have zero interest in becoming residential landlords, and are happy to let the property sit dark for months at a time. These buyers are fully comfortable paying $1,500+ in monthly HOA dues simply to keep the condo empty and immaculate for their personal use a few weeks each year.
This establishes an unbreakable second-home price floor. Even if values dropped further, most local working families would remain structurally disqualified by non-negotiable HOA dues. Under standard debt-to-income (DTI) underwriting, a $1,500/month HOA fee carries the same qualifying borrowing weight as roughly $235,000 in additional mortgage debt, thereby locking out median-income wage earners.
Consider the lending mechanics that were neither understood nor even discussed throughout the county’s countless hours of Bill 9 phase out deliberations.
The median household income in Maui County sits near $100,000. Under standard residential underwriting limits (a 28% front-end housing ratio) at 6.5% interest, that household qualifies for a maximum housing cost outlay of roughly $2,330 per month. On a single-family home with zero HOA dues, that income supports a $300,000 mortgage, translating to a maximum purchasing power of roughly $375,000 with 20% down.
Introduce a luxury resort condo’s mandatory $1,500/month HOA assessment, and the equation implodes. The fixed HOA fee absorbs nearly 65% of the family’s entire allowable housing budget before paying a single dollar toward principal, interest, or property taxes. The remaining cash flow qualifies the household for only $100,000 to $125,000 of mortgage debt, which drops total buying power to roughly $155,000.
Expecting luxury resort condominiums in Wailea or Kapalua to trade down to $155,000 is economic fantasy, regardless of how many vested property rights the county attempts to extinguish.
Fiscal Self-Harm: Turning an Economic Engine into Nothing
Beyond failing to produce a single unit of housing that’s affordable to the median household, eliminating STR rights in resort corridors like Wailea and Kapalua contributes to a collapse in municipal and state tax revenues.
Under lawful short-term rental operations, a single condo functions as a high-yield revenue engine for the public treasury. When that same unit transitions into a shuttered, dark second home, tax collections almost entirely evaporate:
| Tax Category & Jurisdiction | Lawful Active STR ($100K Gross) | Dark / Vacant Second Home | Annual Loss to Public |
|---|---|---|---|
| Maui Real Property Tax | $13,200 (TVR-STRH Tier) | $6,250 (Non-Owner Occupied) | -$6,950 (-53%) |
| Maui County TAT (MCTAT) (3.0%) | $3,000 | $0 | -$3,000 (-100%) |
| Hawaii State TAT (11.00%) | $11,000 | $0 | -$11,000 (-100%) |
| Hawaii General Excise Tax (4.5%) | $4,500 | $0 | -$4,500 (-100%) |
| Total Government Tax Revenue | $31,700 / yr | $6,250 / yr | -$25,450 / unit |
Picking Winners & Losers
By stomping on small businesses and pushing resort condos in Wailea and Kapalua out of commercial operation, Maui lawmakers do not free up “affordable” homes for local families. They simply trade active, heavily taxed, economically productive lodging assets for dark vacation “lock-and-leaves.”
In the process, Bill 9 reduces competition in Maui’s luxury lodging sector to the benefit of big hotel interests that stand to have thousands of their lowest-priced competitors wiped off the map. In Wailea alone, Bill 9 will extinguish STR property rights from 650+ condo units that are literally surrounded by hotels. They will continue to raise nightly rates with impunity while enjoying a property tax rate that is 30% lower than what the most valuable STRs pay.
The other big winners are of course the endless stream of mainland buyers who will jump at the chance to pick up a second, third, or fourth luxury home at a historically cheap price. Freed from the pesky inconveniences of having to share the pool with Airbnb guests and reassured that financial realities will severely limit the number of full-time residents who can live there, these new “lock-and-leave” buyers will eventually come to dominate the Minatoya-list luxury resort complexes in Wailea and Kapalua.
The Legal Battle to Come
The tragedy of municipal land-use law is that a downzoning policy that strips existing property rights does not even have to work to be considered legally valid. Under the deferential “rational basis” test, courts regularly grant local legislators immense leeway to pursue a “public purpose” even when it’s experimental and based on faulty economic assumptions that are entirely divorced from reality.
A judge reviewing Bill 9’s public purpose will be unlikely to audit whether an HOA fee disqualifies a local buyer. Instead, he or she might simply ask if the County Council theoretically intended to help deliver more units of long-term housing, however ill-prepared they might have been to attempt such a fraught undertaking.
But while the County may clear the low bar of establishing the existence of an underlying “public purpose” intent, it still runs straight into the much higher constitutional wall of regulatory takings and statutory vested rights. Stripping decades of lawful reliance to create a policy outcome that benefits out-of-state cash buyers while destroying local tax receipts isn’t just bad governance, it may be the very definition of an uncompensated regulatory taking.
Written by Devin Redmond
Devin is an independent investor and freelance writer focused on the real estate industry. He previously worked at Jones Lang LaSalle, Hines Interests, and Roofstock. He actively acquires and manages residential properties across California and Hawaii.
P.S. Maui isn’t operating in isolation here. Oahu has been running its own version of this fight for years. If you’re trying to understand how these battles tend to play out across the islands, our rundown of Oahu’s short-term rental rules may be a useful comparison.